For business owners approaching an exit for the first time, the world of merger and acquisition activity can feel like it comes with its own language. Terms like earnout, vendor finance, and retained equity get used casually by buyers and advisors who deal in transactions every day, but for an owner going through the process for the first time, understanding the basics of merger and acquisition activity is essential to negotiating from a position of confidence rather than confusion.
This guide covers the fundamentals every business owner should understand before entering a sale process.
What Does Merger and Acquisition (M&A) Mean?
Merger and acquisition - commonly abbreviated to M&A - refers broadly to the combination of companies through purchase, sale, or consolidation. An acquisition is one company buying another; a merger is two companies combining into a new entity.
The two concepts, while related, are technically distinct. An acquisition involves one company purchasing another, with the acquired business typically continuing to operate under new ownership. A true merger involves two companies combining to form a new entity, with shared ownership and governance going forward.
In the mid market, the overwhelming majority of transactions are acquisitions in the true sense. One party, whether a private equity firm, family office, or individual buyer, provides capital to purchase the business, and the seller exits with proceeds from the sale, sometimes retaining a minority stake depending on the structure agreed.
Why Understanding M&A Basics Matters for Sellers
Even though your advisor will manage the technical details of the transaction, understanding the fundamentals of how M&A works puts you in a considerably stronger position throughout the process. You will be better equipped to evaluate offers on their genuine merits, ask informed questions during negotiation, and recognise when a proposed structure genuinely serves your interests versus when it primarily benefits the buyer.
Who Are the Main Buyers in Mid-Market M&A?
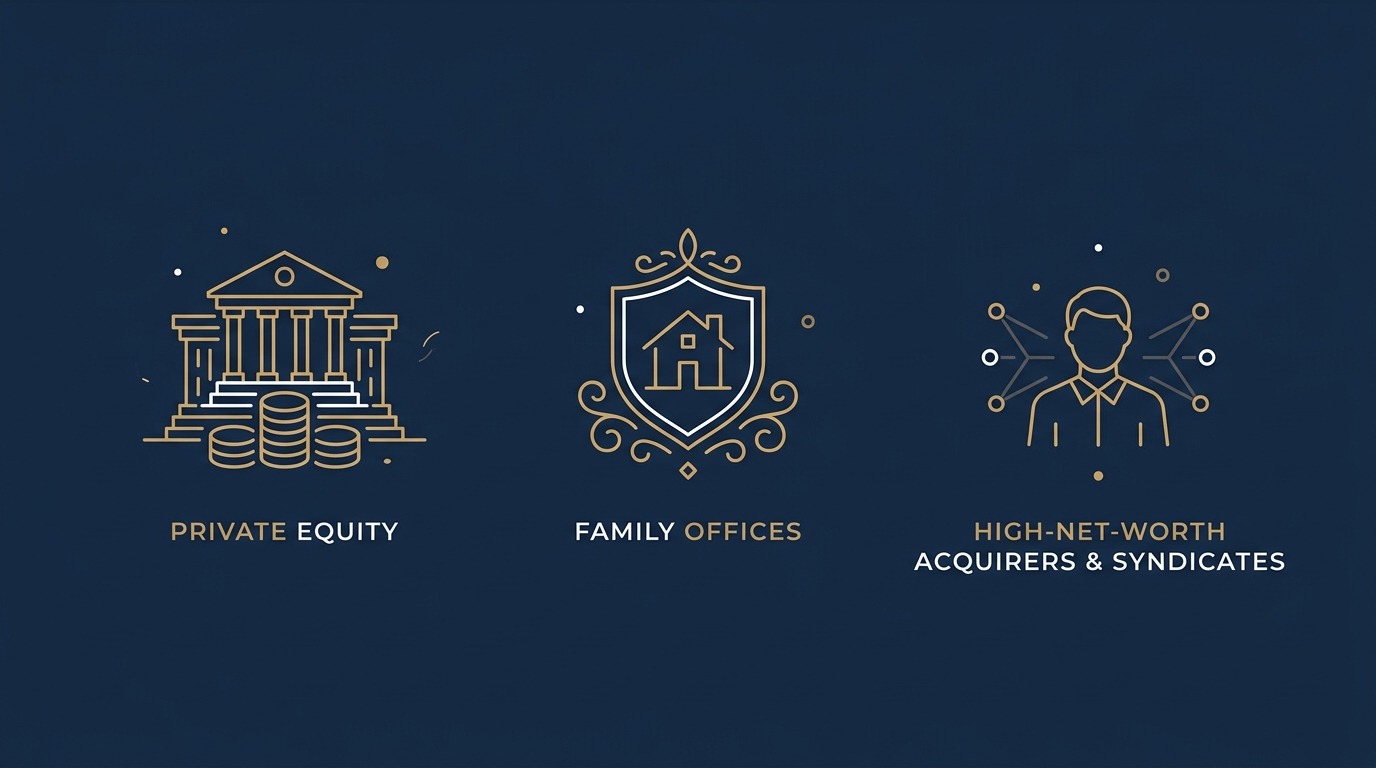
Sellers typically encounter three main buyer categories: private equity firms, family offices, and high net worth individuals or syndicates - each with different priorities, timelines, and flexibility.
Private equity firms acquire businesses using pooled institutional capital, generally with a defined investment horizon of five to seven years before they plan their own exit. They favour businesses with recurring revenue, defensible market positions, and management depth beyond the founder. Our plain-English guide to private equity explains how they operate.
Family offices invest their own capital and typically take a longer term view, often comfortable holding a business for a decade or more. They tend to value stability and cultural continuity alongside financial performance.
High net worth individuals and syndicates may be operating businesses in the same or an adjacent industry, or independent acquirers seeking direct ownership. These buyers sometimes move faster and offer more flexibility on structure than institutional buyers constrained by fund level processes.
What Are the Main M&A Deal Structures?
The four core structures are full cash, cash plus vendor finance, cash plus earnout, and blended structures with retained equity. Understanding these - beyond just the headline price - is one of the most important basics for any seller.
Full cash acquisition. The buyer pays the full purchase price at completion. This offers the seller a clean, immediate exit, though it sometimes comes at a modest discount to headline value because it requires the buyer to be fully capitalised upfront.
Cash plus vendor finance. A portion of the purchase price is deferred, with the seller effectively financing part of the transaction over an agreed period, often around two years. This can achieve a higher headline price for the seller while reducing the buyer's upfront capital requirement.
Cash plus earnout. Part of the purchase price is contingent on the business achieving agreed performance targets after completion. This structure aligns risk between buyer and seller, but requires careful negotiation of the targets and mechanics to avoid future disputes.
Blended structures with retained equity. More complex transactions may combine cash, deferred finance, and a retained equity stake for the seller, allowing the buyer to preserve capital while giving the seller ongoing exposure to the business's future growth.
How buyers fund these structures is covered in our guide on financing a business acquisition.
What Are the Stages of the M&A Process?
A typical M&A transaction moves through several distinct phases: confidential briefing, valuation guidance based on real market appetite, preparation of an investment grade Information Memorandum, private buyer outreach to a pre qualified network, negotiation of an indicative offer, due diligence, and finally, structuring and negotiation through to settlement.
Each of these stages carries its own risks and opportunities for a seller to protect or improve their outcome, which is why experienced representation throughout the entire process, rather than just at the negotiation stage, makes a material difference. Our step-by-step business sale process and ultimate due diligence guide walk through the stages in detail, and an honest valuation is a sensible first step.
Common Misconceptions About M&A
Many first time sellers enter the process with assumptions that do not hold up in practice. A common one is that the highest headline offer is automatically the best offer, when in reality the structure attached to that price, including how much is paid upfront versus deferred, often matters just as much as the number itself. Another is that a public listing will attract more buyer interest than a private, advisor led process, when the opposite is usually true in the mid market, where quality buyers actively avoid public listings in favour of private, pre qualified opportunities. A third is that due diligence is a formality, when in reality it is where a significant proportion of deals are renegotiated or, in some cases, abandoned entirely.
Why Experienced Representation Matters in M&A
Merger and acquisition transactions involve sophisticated counterparties who negotiate deals professionally and regularly. An unrepresented seller, or one working with a generalist advisor unfamiliar with mid market M&A specifically, is at a structural disadvantage from the very first conversation. Specialist representation brings access to a pre qualified network of genuine buyers, the credibility of a properly prepared investment memorandum, and the structuring expertise to negotiate terms that protect the seller's outcome - which is how the right advisor maximises your sale price.
Blackmont Advisory is a boutique, senior led M&A firm based in Melbourne with a global network of buyers, investors and partners. We manage every mandate from first meeting through to settlement, never representing both sides of the same transaction, so our advice is structured independently for you. Whether you are considering a sale or exploring an acquisition, understanding these basics is the first step toward a transaction that genuinely serves your interests. For a deeper dive, see our complete guide to selling a business or guide to buying a business.
If you are weighing up your options, a confidential, no obligation conversation is the natural place to start before any formal process begins.
Selling? Start with a confidential valuation. Buying? Register your acquisition brief.
Frequently Asked Questions
What does M&A (merger and acquisition) mean? M&A refers to the combination of companies through purchase, sale, or consolidation. In an acquisition, one company buys another that then operates under new ownership. In a merger, two companies combine to form a single new entity with shared ownership and governance.
What is the difference between a merger and an acquisition? An acquisition is one company purchasing another, with the target continuing under new ownership. A merger is two companies combining into a new entity. In the mid market, the overwhelming majority of transactions are acquisitions rather than true mergers.
Who are the main buyers in mid-market M&A? Three main categories: private equity firms (institutional capital, five-to-seven-year horizon), family offices (their own capital, longer holds, value stability), and high net worth individuals or syndicates (often faster and more flexible on structure).
What are the main M&A deal structures? Full cash acquisition, cash plus vendor finance, cash plus earnout, and blended structures with retained equity. The right structure depends on both parties' risk appetite, the buyer's capital, and the seller's objectives — the structure often matters as much as the headline price.
Is the highest offer always the best offer? No. The structure attached to a price — how much is paid upfront versus deferred through vendor finance or an earnout — often matters as much as the headline number. The highest headline offer is not automatically the best outcome once terms and certainty are considered.